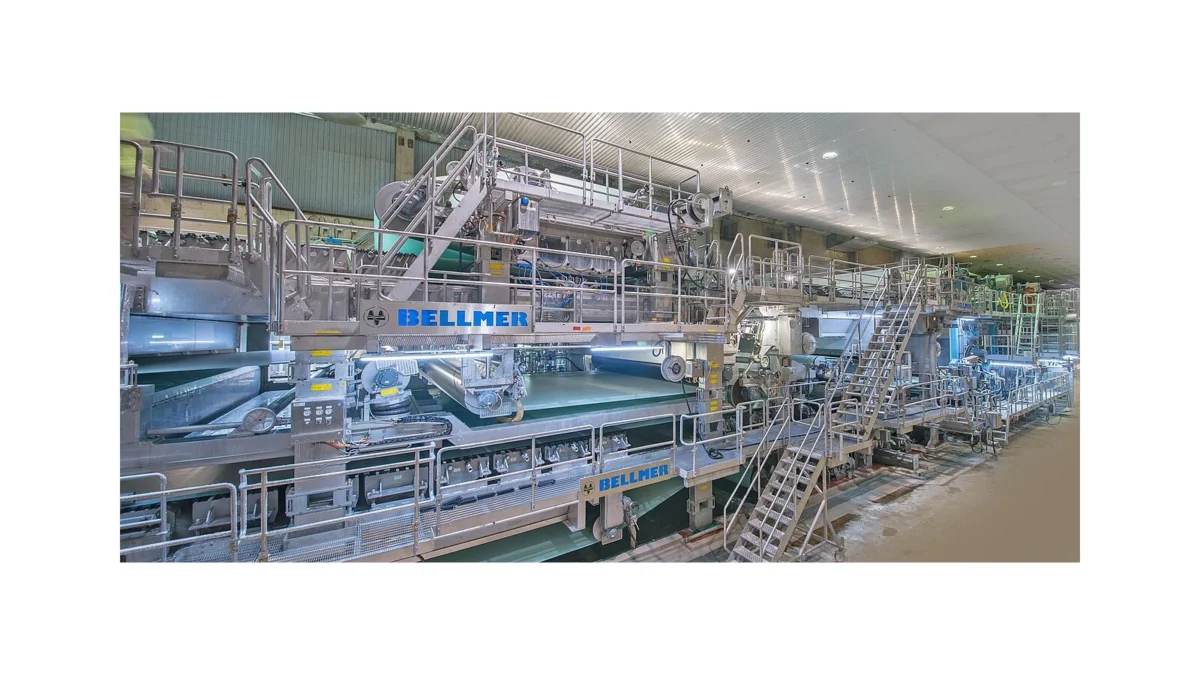
European paper and board production fell by 1.6% to 77.4 million tonnes in 2025, according to the Confederation of European Paper Industries (Cepi) in its 2 July 2026 Key Statistics release. That headline could suggest a uniform decline across paper packaging. The underlying picture is different: Cepi describes production of packaging grades as broadly stable, while cartonboard contracted by 5.4% and graphic paper by 7.3%. Early 2026 output was already down 2.4% in the first quarter against the equivalent period a year earlier. [S1]
Related analysis: the difference between packaging waste and market demand.
For packaging buyers, this is a reminder that ‘paper and board’ is an industrial grouping, not one market. Corrugated transport packaging, retail folding cartons, wrapping papers and printing papers do not have identical demand patterns, converting requirements or supply constraints. A strategic purchasing decision based on the aggregate number alone may therefore be wrong.
What the 2025 figures actually measure
Cepi reports production across its participating European paper-industry countries. This is not a census of every mill in the world, and it should not be presented as the exact output of the EU-27 without checking the geographic coverage in the detailed report. The figures reflect manufactured output, not retail packaging demand or the revenue value of finished cartons. [S1]
| Indicator | Cepi reporting | Editorial reading |
|---|---|---|
| Paper and board production, 2025 | 77.4 million tonnes | Broad industry volume, not packaging sales alone |
| Annual change | -1.6% versus 2024 | Year-on-year output contraction |
| Packaging grades | Broadly stable | Stability can hide diverging subgrades |
| Cartonboard | -5.4% | Retail-carton substrate weakness in the reported production measure |
| Graphic paper | -7.3% | Structural decline outside much of food and transport packaging |
| First-quarter 2026 output | -2.4% year over year | Early signal, not a full-year 2026 outcome |
The report is an industry body release. It is a primary record of the association’s reported statistics, though the association also advocates for its member companies. Distinguishing the data from its policy recommendations is essential.
Packaging paper is not moving as one commodity
The February 2026 preliminary statistics offered an additional subgrade view: estimated containerboard production rose 1.7%, cartonboard fell 5.6% and wrapping paper increased 1.0%, while total packaging grades were nearly unchanged at +0.2%. These were preliminary figures. Cepi’s July release gave updated full-year values and should take precedence where a later number is supplied. [S2] [S1]
There is a substantive market message in this split. Containerboard serves corrugated shipping and transport applications, whereas cartonboard is used extensively for folding cartons in food, personal care and consumer goods. Different demand channels can produce different changes in mill output, even in a year when the broad packaging category appears stable.
It would be too strong to claim that e-commerce alone caused all changes in containerboard or that consumer spending alone explains cartonboard weakness. The public statistics do not isolate those drivers. Production also responds to inventory, imports, exports, capacity downtime, maintenance and price competitiveness.
The editorial conclusion is narrower but useful: packaging buyers should monitor the grade they actually buy, rather than use a paper-industry headline as a proxy for their product. A corrugated-box procurement manager and a premium folding-carton buyer may face quite different negotiating conditions.
Output decline is not the same as a demand collapse
One of the recurring mistakes in packaging-market reporting is equating lower production with lower end-user consumption. Domestic mills can produce less because imports displace local output, because plants close or because energy costs make operation unattractive. None of these necessarily means brands purchased the same percentage less packaging.
Cepi says import penetration reached a record 7.7% of EU consumption in 2025, while exports still accounted for more than a fifth of production. Those figures come from different indicators and require careful geographic interpretation. They suggest trade competition matters to the industrial picture, but they do not establish a single cause for the output decline. [S1]
A packaging distributor observing stable customer order volumes while a domestic mill curtails production could therefore be seeing a shift in supply origin rather than a market collapse. To investigate that hypothesis, one would need trade tonnage by grade, inventories and the purchasing price basis for the destination market.
Why energy and capacity matter to packaging supply
Pulp and paper production can be energy- and capital-intensive. The economics differ by mill technology, integration, fiber mix and local utility prices. Cepi cites industrial costs and competition as important pressures; these are the industry’s stated explanations, not a causal decomposition supplied in its public summary. [S1]
For a buyer, the implication is to watch supplier continuity as well as nominal price. A mill operating with low utilisation can face pressure to rationalise product ranges or consolidate capacity. But it can also seek higher-volume customers aggressively. The correct purchasing response depends on the actual supplier’s financial and operational circumstances, not on a general European trend alone.
It is equally important not to infer immediate packaging shortages from an aggregate production decline. Packaging conversion uses inventories, multiple mills, imports and alternative grades. A 1.6% industry contraction does not automatically translate into unavailable cartonboard or higher end-user box prices.
What the mid-year data tells us—and what it does not
The first-quarter 2026 decline of 2.4% is a warning signal in the July Cepi release. It does not establish the full-year production total, nor does it provide a forecast for every paper grade. A weak first quarter can be followed by recovery, further weakness or shifts between grades. [S1]
Market analysis should therefore retain separate columns for observation period and release date. The observation year here is 2025. The later publication date is July 2026. A report published in 2026 is not automatically a report of calendar-year 2026 production.
The difference between Cepi’s February preliminary and July key-statistics releases also illustrates revision risk. The preliminary headline decline was 1.5%; the later headline was 1.6%. That is a small numerical change, but it matters for charts and references claiming to use the latest available full-year figure. [S2] [S1]
A decision framework for buyers and converters
| Business decision | More useful measure than the headline |
|---|---|
| Contracting corrugated boxes | Containerboard availability, converter capacity and delivered price |
| Sourcing food folding cartons | Relevant cartonboard grade, coatings, lead time and print yield |
| Considering a new converting line | Local order mix, achievable machine utilisation and waste per approved job |
| Assessing paper vs plastic substitution | Required barrier, protection performance and actual recovery system |
| Tracking supply resilience | Regional production, imports, mill shutdowns and supplier diversification |
This table is an editorial procurement framework, not a price forecast. The data needed to complete each decision would be supplier- and market-specific.
Industry viewpoint: the ‘slow drift’ diagnosis
Cepi Director General Jori Ringman characterises the reported trend as an erosion of the region’s industrial base and calls for more predictable investment conditions. His position reflects the interests of the European paper industry. It is nevertheless a useful warning that a gradual capacity shift can matter more to long-term supply resilience than one dramatic quarterly figure. [S1]
We would add a necessary qualification: market resilience is not measured only by where a tonne of board is made. Buyers also need reliable quality, competitive pricing, functional packaging performance, legal compliance and access to appropriate recovery infrastructure. Increasing European production without improving these outcomes would not automatically deliver a better packaging system.
Editorial assessment: watch the grade and the trade flow
The key fact from Cepi’s 2025 data is not simply that European paper production shrank. It is that packaging-grade performance diverged materially from the wider industry, and cartonboard did not match the relative stability of the broad packaging grouping. The next research priority should be updated grade-level production, import dependence and converter order patterns, not an unsupported single-number forecast for the global paper-packaging market.
Buyers should keep production, apparent consumption and trade flows in separate series, and retain the release vintage when comparing grades. That prevents a revised mill-output figure from becoming an unsupported packaging-demand forecast. [S1] [S2]
Sources / References
- [S1] Cepi — A Slow Drift: 2025 Key Statistics press release, 2 July 2026. Current published summary used for 77.4 million tonnes, -1.6%, cartonboard -5.4%, graphic paper -7.3% and 2026 Q1 -2.4%. Full relevant web text reviewed.
- [S2] Cepi — Preliminary Statistics 2025 press release, 17 February 2026. Earlier provisional subgrade comparison; do not silently replace revised July numbers with preliminary values.
Found an error? Read our corrections policy and contact the editors.