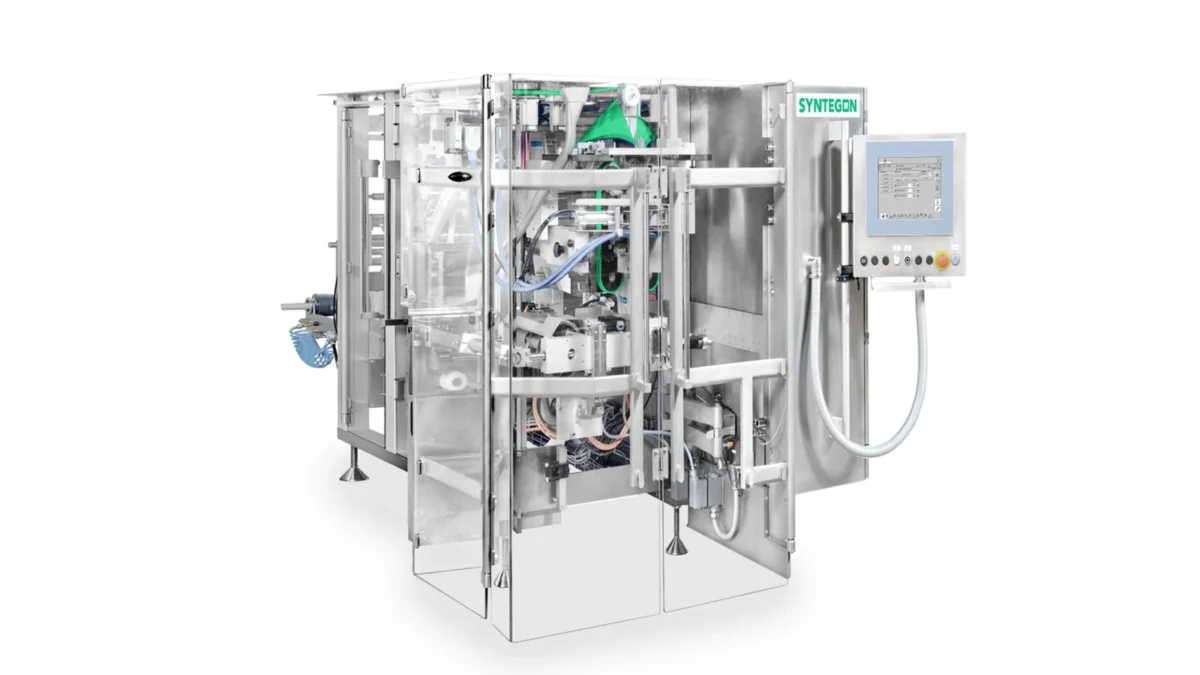
Packaging equipment buyers are asking for machines that can handle more products, thinner materials and a less predictable flow of capital spending. That is the commercial message in PMMI’s 2026 Packaging Machinery Market Trends, released on 11 November 2026. The report brings together packaging machinery supplier interviews, research with Interact Analysis and secondary market evidence. It describes changing procurement behavior; it is not a census of every US packaging plant. [S1]
For related context, read our analysis of plant-level retrofit versus replacement decisions.
The most useful reading of the new study is not that one technology has won. It is that the acceptable equipment specification is changing. Flexible machinery, asset preservation and the ability to document machine performance are increasingly part of the purchasing conversation. That shifts the question from “How fast is the machine?” to “How reliably can the line meet tomorrow’s assortment and material specifications?”
Longer buying cycles are an engineering signal
PMMI reports that machinery suppliers are encountering greater price sensitivity and longer, more fragmented sales processes. It also identifies rapid changes in product popularity and SKU proliferation as pressure points. A consumer product that succeeds unexpectedly can demand another pack size, closure or promotional format before a long-life packaging line has recovered its investment. [S1]
A supplier dealing with that uncertainty must support a buying process with clearer boundary conditions. Minimum and maximum package dimensions, product viscosity, film gauge, cycle speed, cleaning requirements and the number of scheduled changes may matter more than a single peak-throughput figure.
The longer cycle also creates opportunities for staged validation. A credible proposal can offer material trials, modular retrofits and a layout showing what later expansion would involve. That is not the same as assuming every buyer can postpone replacement indefinitely. A worn drive, inaccessible control architecture or physically constrained forming station can make an upgrade more expensive than replacing the machine.
Three trends that change the specification
| Signal in PMMI’s November report | Operational implication | What still needs plant-level proof |
|---|---|---|
| More SKUs and variable demand | Faster and more repeatable changeovers | Actual changeover losses on the buyer’s product mix |
| Thinner films and reduced material | Tighter control of tension, sealing and handling | Yield and integrity at the proposed material gauge |
| Higher interest in modular systems and retrofits | Equipment designs that can be upgraded | Installed-base condition, controls compatibility and total cost |
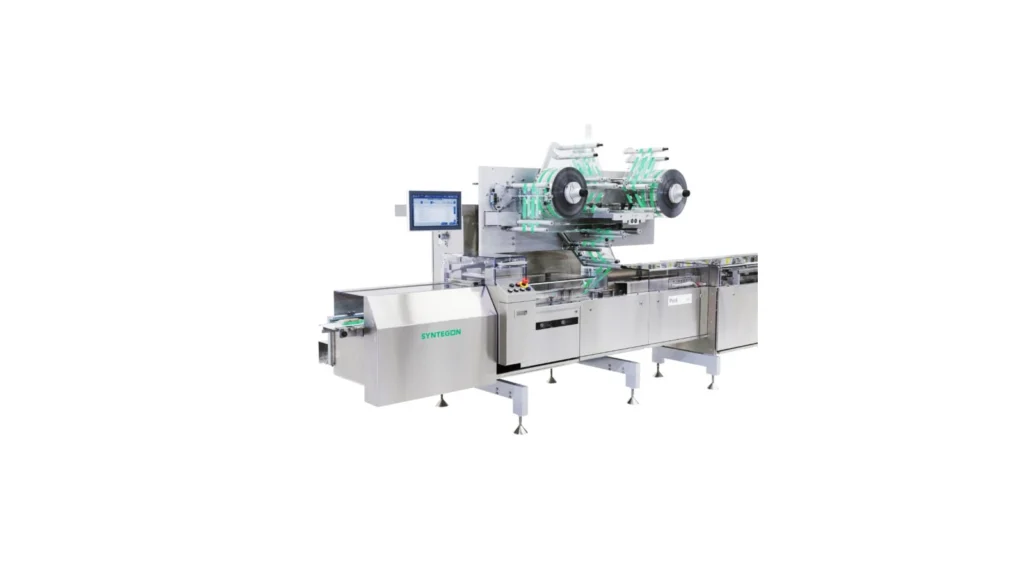
PMMI’s research points to machinery capable of handling plastics and fiber-based alternatives as material strategies evolve. The phrase capable of handling should be treated carefully: a web-fed paper substrate, a wet molded-fiber tray and a flexible plastic film do not pass through the same forming and sealing stations merely because they serve the same product category. Compatibility has to be demonstrated by substrate, geometry and process. [S1]
The narrower material window
Lightweight packaging is often presented as a straightforward saving. On a production line, reducing thickness changes how the material behaves. Films may stretch differently, wrinkles can form at the seal area, and the margin between insufficient sealing and heat damage may narrow. A machine that ran a previous specification at nominal speed may need changed sealing jaws, tension controls, tooling or inspection thresholds.
The editorial implication is that material-reduction projects need two business cases: one for material purchased per acceptable pack and another for lost output, scrap and maintenance. A thinner film that saves material in the laboratory but causes frequent line stops is not yet a successful commercial redesign.
The same principle applies to fiber alternatives. A preformed tray must be dimensionally stable enough for destacking, denesting, filling, sealing and lid application. The machinery trial must include actual production tolerances rather than one carefully selected sample.
AI is appearing first in ordinary information problems
The November report describes AI in knowledge capture, specification reuse, internal information retrieval and digital visibility. These uses are less visually dramatic than fully autonomous factories, but they address recurring losses of institutional knowledge. A manufacturer may already have solved a difficult material or tooling problem on a previous project; a searchable engineering record can prevent the team from rediscovering the same answer. [S1]
There is a limit to what a language model should do in this environment. A generated specification can help locate precedent and draft questions, but it should not silently supply a tested sealing temperature, regulatory conclusion or validated cycle-time guarantee. The source record, revision and approving engineer still matter.
PMMI’s separate February 2026 AI report, based on 14 expert interviews and secondary research, also identifies machine vision and workforce knowledge transfer among practical application areas. It does not establish that a single AI system is suitable for every packaging line. [S3]
The equipment investment is not the market headline
PMMI’s September announcement of its State of the Industry research puts the estimated value of US domestic packaging machinery shipments at $11.7 billion in 2025, with food comprising approximately 44% of that value. That is shipment value, not total machinery operating stock, an estimate of plant retrofit spending or the value of every packaging material sold. [S2]
Those definitions matter because the November study is more about the quality of demand than a newly reported market total. A company should not use a broad equipment market estimate to justify a machine purchase without determining the line-specific constraint.
Jorge Izquierdo, PMMI’s vice president of market development, described the sector in September as handling more SKUs, more formats and more automation while making capital spending count. His observation is a supplier-side industry perspective, consistent with the November trends, but it is not a statistical estimate of how many factories have converted to modular machinery. [S2]
What operators should ask equipment vendors
A useful request for proposal should include a product-and-pack matrix rather than a generic list of machine features. For each proposed pack, specify the substrate and its tested variation, nominal package dimensions, realistic operating speed, minimum and maximum changeover interval, quality acceptance criteria and downstream case or pallet configuration.
Ask the supplier to show the worst changeover, not only the easiest demonstration. Request separate figures for stable running rate, first-article release, setup labor, rejected startup packs and cleaning time. If the system is designed for upgrades, identify the interface, software license, spare capacity and validation work that would actually be required.
These details bring procurement back to the manufacturing task. A machine with a high catalogue speed and weak flexibility may be appropriate for a stable, single-format product. A slower modular machine may be economically better for short runs. Neither is inherently the stronger investment.
The next test of PMMI’s thesis
The evidence to monitor after this release is not simply another headline about automation. It is whether suppliers begin disclosing more consistent figures for orders, retrofits, installed-base services and repeatable format-change performance. For buyers, the corresponding test is whether promised flexibility survives full-speed trials with commercially sourced materials. That is the difference between a compelling trend and a working factory capability.
Sources / References
- S1. PMMI, 2026 Packaging Machinery Market Trends, published 11 November 2026. Public report summary; interviews and benchmarking are described, but gated report detail not independently examined.
- S2. PMMI, 2026 State of the Industry report release, 14 September 2026. Full public release; $11.7bn US domestic shipment value and end-market share; named executive perspective.
- S3. PMMI, 2026 Building an AI Advantage in Packaging Equipment, 3 February 2026. Public summary and methodology only; no unverified full-report conclusions.
Found an error? Read our corrections policy and contact the editors.